Somewhere around 50, everyone starts handing you the same script: the kids are gone, so sell the big house and go small.
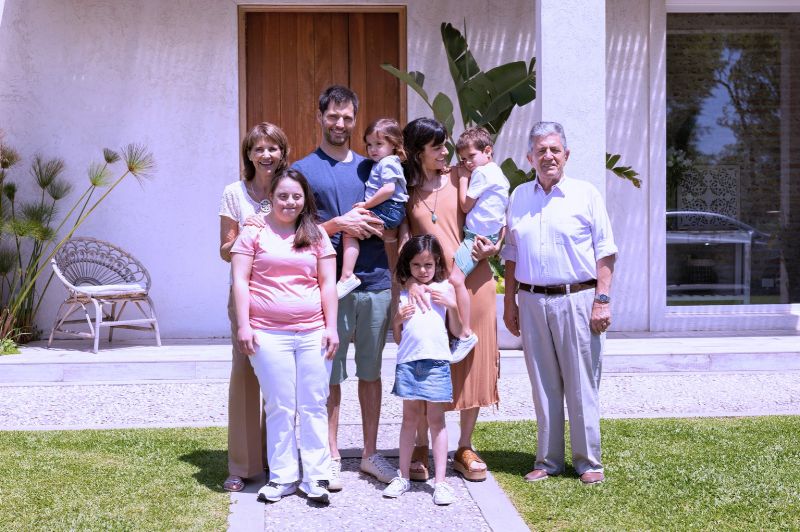
There’s a real case for that, and we’ve made it ourselves in Downsizing After the Empty Nest. What nobody mentions is that the family might rearrange itself first. Maybe your 27-year-old is back in his old room with a laptop and strong opinions about rent. Or your mother can’t manage the stairs at her place anymore. Suddenly the question isn’t how small you can go. It’s whether you’re buying a multigenerational home.
And if you’d only just gotten the quiet back, that stings. The spare room had finally turned into your office, and dinner was whatever you felt like at 8 p.m. Saying yes to your people out of love doesn’t cancel the part of you mourning the life you’d barely started. That part gets a vote, too.
You’re in crowded company. The National Association of Realtors asked recent buyers of multigenerational homes why they bought: 41% said to care for aging parents, and 27% said adult children were moving back in. Gen X leads the way, with 19% of Gen X buyers purchasing one in the past year, per NAR’s 2026 generational report.
So yes, sizing up can be the right call. Just make it your call, not something you slide into because somebody needs a bedroom.
Before Buying a Multigenerational Home, Name Who’s Moving In
A boomerang kid and an aging parent are very different houseguests. One is probably temporary and needs a door that closes. The other may be permanent, may need more help every year, and may need a first-floor bedroom sooner than anyone wants to say out loud. Which one are you buying for? It might be both.
Pew Research Center found that about a quarter of adults in multigenerational homes call it stressful all or most of the time, while more than twice as many call it rewarding most of the time. Plenty of people feel both in the same afternoon.
When a parent moves in, someone becomes the caregiver, and you already know who it usually is. AARP’s Caregiving in the US 2025 report puts numbers to it. Three in five family caregivers are women, and the average caregiver is 51. Before the offer goes in, ask who’s driving to the 2 p.m. cardiology appointment on a Tuesday. If the answer is automatically you, say so while there’s still time to divide the load. Our piece on helping your parents age well is worth a read first.
Layout Matters More Than Square Footage
A bigger house with the wrong layout just gives everyone more rooms to argue in. These matter more than the total square footage:
- A bedroom and full bath on the main floor
- A suite, finished lower level, or separate entrance that gives someone real privacy
- Enough bathrooms that nobody is negotiating at 7 a.m.
- At least one step-free way into the house
If we had to pick one, it’s the main-floor bedroom, because it’s the hardest thing on that list to add later.
Picture the body you’ll live in at 70, too. In AARP’s 2024 Home and Community Preferences Survey, 75% of older adults said they want to stay in their homes, yet 44% of adults 50+ expect they’ll have to move at some point. A house you can age in keeps your options open.
And your room is not whatever’s left after everyone else gets settled. You’re the one signing for this place.
The Mortgage Math at 55 Isn’t the Math at 35
On paper, the law is on your side. The Consumer Financial Protection Bureau says a lender generally can’t deny you a mortgage or charge you more because of your age. Your timeline still counts, though: a lender can weigh how close you are to retirement and whether your income will last the life of the loan.
Mortgage debt is following a lot of people into retirement. Between 1989 and 2022, Harvard’s Joint Center for Housing Studies found, the share of homeowners 65 to 79 still paying a mortgage rose from 24% to 41%, and their median mortgage debt jumped from $21,000 to $110,000. A new 30-year loan at 55 runs until you’re 85. We won’t call that a mistake. We’d just want you to sign it with that end date in plain view.
On a hypothetical $320,000 loan at 6.5% over 30 years, principal and interest come to about $2,023 a month, before property taxes, homeowners insurance, or any mortgage insurance.
When several people are chipping in and any one of them could move out, predictability matters. A fixed-rate mortgage loan locks your interest rate, so the principal and interest stay the same for the whole term, even as the household around it changes.
The monthly payment is only one number. What’s the total interest over the life of the loan? Would a shorter term, or a bigger down payment from your current home, keep this debt from following you into your 70s? Those are worth answering before you fall for the kitchen.
Put the Money Talk in Writing Before Move-In Day
NAR found that more than one in four multigenerational buyers have three or more people contributing to household income, compared with 11% of other buyers.
Pooled income helps when you’re buying a multigenerational home. But if the loan is in your name, the lender doesn’t care that your son promised to cover $800 a month. A few questions to answer before anyone carries a box inside:
- Who pays what, and what happens if someone stops paying?
- Whose name goes on the title, and what does that mean for your estate?
- What happens when someone moves out, partners up, or needs more care?
Our blunt take: if your family’s arrangement can’t survive being written down, it won’t survive the first missed payment either. An hour with a real estate attorney or financial advisor costs far less than a family fight over a house you’re still paying off.
Your Equity Is Your Retirement, So Guard It
The money you pull out of your current home may be the biggest asset you’ll have at 70.
Selling for $400,000 doesn’t put $400,000 toward the next place. Your mortgage payoff, agent commissions, buyer-requested repairs, closing costs, and the move itself all come out first. Mismatched closing dates can mean two housing payments at once.
Then the bigger house starts sending bills. The Cooperative Extension’s Financial Security for All team puts typical maintenance and repairs at 1% to 3% of a home’s value per year, which is $4,500 to $13,500 on a $450,000 house. Call it a rough guide; a 20-year-old furnace can blow through it in one winter. A full inspection will tell you what you’re inheriting.
Caregiving takes its own cut. In that same AARP report, more than a third of caregivers had stopped saving, and 13% had dipped into long-term savings such as retirement accounts. Opening your home is one decision. Funding everyone’s comfort with your retirement is another.
Bigger Can Still Be Yours
You’ve spent decades making room for everyone. Doing it again in a bigger house can be generous, even joyful. It can also quietly shrink your life if the only thing that grows is your list of obligations.
So if buying a multigenerational home is where your life is headed, go bigger. Put your name on the loan, then put it on a door, and don’t apologize for either one.
Disclaimer: This article is for general information only and is not financial, legal, or lending advice. Talk with a licensed professional about your situation.
Did you enjoy this contributed article? This post contains affiliate links. Sign-up for our Sunday newsletter and get your expert content delivered straight to your inbox.